

How to Get UPI From the US Without an Indian SIM
You don’t need an Indian SIM to use UPI from the US. Here’s how NRIs register a +1 number, link an NRE or NRO account and start sending rupees home.
 by Amira Bula
You can get UPI India access from the US without an Indian SIM. You need an NRE or NRO account with a participating bank, and your US number (+1) has to be registered on it.
Add an app that supports international numbers and the whole setup happens from your phone, before any flight.
If India is on your travel list, an India eSIM keeps you connected from the moment you land.
What do you need before you start?
You need an active NRE or NRO account, a bank that supports international numbers, your +1 number on file with that bank, a compatible app, and a phone plan that can receive international SMS.
| Requirement | What it means |
|---|---|
| NRE or NRO account | Active, with KYC complete. A resident savings account won’t work. |
| A bank that supports international numbers | IDFC First, ICICI, HDFC, Axis and Federal are among the banks that do, but check with yours. |
| Your +1 number on the account | Set as the primary contact through net banking, the bank’s app, email or its NRI helpline. |
| A supporting app | PhonePe, Google Pay (India version), BHIM or Paytm, depending on your bank. |
| International SMS on your US plan | Needed for the verification code during setup. |
NPCI opened UPI India registration to international numbers from 12 countries, and the USA is one of them.
The others are the UK, Canada, Australia, Singapore, the UAE, Saudi Arabia, Qatar, Oman, Hong Kong, France and Malaysia. Rollout still varies by bank and app.
The paperwork sits with the account, not with UPI. Opening an NRE or NRO account takes your passport, proof of NRI status or overseas address, and a PAN or Form 60. Some banks also ask for Aadhaar or visa and residency proof. For UPI itself, your registered international number and your debit card details are enough in most cases, so no extra Aadhaar.
How do you set up UPI from the US, step by step?
You can finish the entire setup remotely, without traveling to India, as long as your bank already holds your KYC.
- Check that your NRE or NRO account is active and that your bank supports international numbers for UPI.
- Ask your bank to register your US number (+1) as the primary contact on the account.
- Download a UPI app that works with international numbers.
- Open the app and enter your full number with the +1 country code.
- Enter the SMS code the app sends to that number.
- Select your NRE or NRO account when the app detects it.
- Set your UPI PIN, usually with your debit card details.
- Create your UPI ID.
- Send a small test payment.
Step 2 is where most setups fail. Skip it and the app can’t find your account. Expect a lower limit on a brand-new UPI ID too, around ₹5,000 for the first 24 hours on Android and 72 hours on iOS.
Which UPI apps work with a US number?
PhonePe, Google Pay, BHIM and Paytm all work with a US number, provided your bank supports international numbers and your +1 is registered on the account.
PhonePe tends to be the smoothest for NRIs. Google Pay works too, though you’ll usually need the India version.
BHIM is the official NPCI app and supports international numbers by default. Paytm works with select banks, IDFC First and ICICI among them. Your bank’s own app, such as ICICI iMobile or the IDFC First app, is a solid route as well.
Confirm with your bank before downloading anything. Support differs from one bank and app to the next.
Do you need an SMS every time you pay?
No. SMS matters mostly during setup, when the app sends a verification code to confirm that the number is yours and active on that phone. That ties your number and device to your UPI profile.
After that, each UPI payment runs on your UPI PIN, fingerprint, face scan or in-app confirmation.
Some actions still call for a text: resetting your UPI PIN, moving to a new phone or reinstalling the app, linking another bank account, and certain large or high-risk transactions, depending on your bank’s rules.
NPCI has also been recognizing silent mobile verification more widely in 2026, which cuts the reliance on SMS further.
It remains the fallback for many apps and banks though, so keep your registered number able to receive texts.
When should you set it up before a trip to India?
Before your flight. Registration needs that SMS code, and once it’s done, UPI India doesn’t ask you to register again when you land.
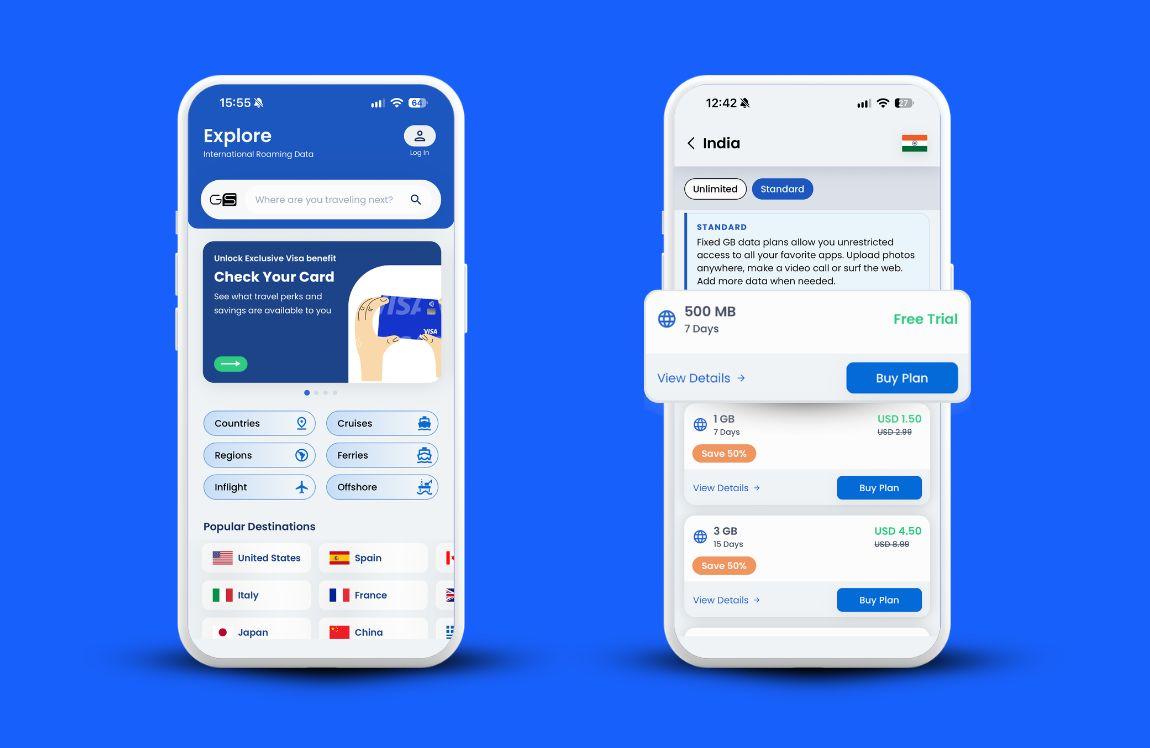
An India eSIM covers the connected part. Install it from the GigSky app before you leave and it connects automatically on arrival, with no manual activation and no India SIM to buy.
Your US SIM stays in the phone, which keeps the number linked to your UPI profile active alongside it.
Your phone does need to support eSIM, and verification texts still go to your US number, so leave international SMS on.
Every UPI payment at a taxi stand, restaurant or shop needs data on your phone, and that’s what the eSIM is for.
You scan the QR code and confirm with your PIN, same as any resident. Websites and apps that accept UPI work too.
What can you do with UPI once it’s set up?
UPI lets you send rupees to any UPI ID, UPI-linked mobile number or bank account in India, instantly and at any hour. Parents, rent, school fees, a utility bill. It all runs from your phone.
The money moves in rupees only, from your NRE or NRO balance. Transfers from NRE to NRE, NRE to NRO, and from either account to a resident account are allowed. NRO to NRE isn’t. You can’t send foreign currency or pull from a US account.
In most cases, UPI India gives NRIs the same limits as residents: up to ₹1 lakh (100,000 rupees) a day or 20 transactions, with some banks setting lower caps. Education and insurance payments can go higher.
Person-to-person transfers are free. Most merchant payments are free to you as well.
From mid-October 2026, merchants may pay a fee on larger transactions above ₹2,000, but it isn’t charged to you.
There’s no forex charge either, since everything is already in rupees. Always confirm current terms with your bank.
Can you use UPI without an Indian bank account?
Not for full UPI. Standard UPI needs an NRE or NRO account holding rupees, so you can’t make a UPI payment in US dollars or pull money straight from a US bank account.
To get dollars into your Indian account, use a remittance service such as Wise, Remitly or Xoom, or send a bank wire. Wise is often competitive on rates and transparent on fees.
Others may run promotions or move money at different speeds. Once the money lands in your NRE or NRO account, moving it around India with UPI is free and instant.
With no Indian account at all, UPI One World is the fallback. It’s a prepaid rupee wallet for visitors and NRIs.
You load it with an international card or cash after passport and visa KYC, then scan UPI QR codes at merchants. It only handles payments to merchants, can’t send money to people, and has balance caps.
Why isn’t UPI working with your US number?
Usually the bank doesn’t have your number on file. Update first. This is the most frequent cause.
If the SMS code never arrives, international texting delays or carrier blocking of Indian short codes are the likely reasons.
Turn on international SMS, try during Indian business hours, check your spam folder, or choose another verification method if the app gives you one.
Some banks haven’t switched on international numbers yet. IDFC First and ICICI are among the more reliable, so ask your bank or consider moving your account.
Account status matters too: a dormant account, expired KYC, or a resident savings account used in place of an NRE or NRO account will all block the link. Check the UPI app version as well, since Google Pay needs the India one.
On an iPhone, registration sometimes works only over mobile data rather than Wi-Fi. And enter your full number with the country code in the same format your bank has on file.
Still stuck? Contact your bank’s NRI desk. They can check the backend linkage.
FAQs
Can NRIs use UPI with a US number?
Yes. If your bank supports international numbers and your +1 is registered on your NRE or NRO account, you can register and pay with it.
Can you pay with US dollars through UPI?
No. UPI moves rupees from an Indian NRE or NRO account. Fund that account first with Wise, Remitly, Xoom or a bank wire.
Does UPI India charge NRIs a fee?
Person-to-person transfers are free, and no special NRI fees have been reported for standard use. Confirm with your bank.
Can you use UPI during a trip to India?
Yes. It works at shops, restaurants, taxis, and on websites and apps that accept UPI, with no re-registration. A data connection is all you need, and a GigSky India eSIM covers that.
Try GigSky Free
Recap: How to Get UPI From the US
- An NRE or NRO account with a bank that supports international numbers is the starting point.
- Register your +1 number with the bank before you open any app.
- PhonePe, Google Pay (India version), BHIM and Paytm all work, depending on your bank.
- SMS is needed at setup and for occasional high-security actions, not for every payment.
- UPI moves rupees only, so fund your Indian account first with a remittance service.
- Set everything up before your flight, then install a GigSky India eSIM so your phone is connected when you land.